 Jaswant Kaur
.jpg)
Last week, while we were busy reading about global developments on the Israel-Iran front and the role US President Donald Trump played in negotiating a "ceasefire," an important piece of news slipped into the news cycle. Under normal circumstances, it would have, perhaps, dominated headlines.
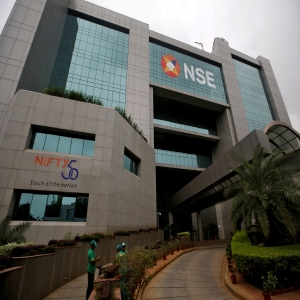
The National Stock Exchange (NSE) — India's largest stock exchange and one of the key pillars of the country's capital market — reached out to the Securities and Exchange Board of India (SEBI) with a proposal to settle long-pending issues and disputes through a ?1,400 crore settlement. Until a month ago, the amount was ?1,000 crore.
Many would think: "What is new in this?" It appears to be the most practical way of closing matters by compensating for losses. Another question comes to mind: "Why is the regulator not prescribing the compensation? Who has the authority to fix the fine or penalty for any kind of irregularity? Should an institution at fault approach the regulator with an amount to close pending matters?"
Let us delve a little deeper to understand what compelled the NSE to approach SEBI in the first place. The events date back to 2010 when the NSE allegedly granted preferential access to its trading servers to a select group of high-frequency trading (HFT) firms. Through colocation, these firms were able to place their systems physically closer to the exchange's servers.
This allowed some firms to receive "tick-by-tick (TBT) data" faster than others. In high-frequency trading, even a "microsecond's advantage" can tilt the entire playing field in favour of a few. This was not just a matter of innovation or legal grey zones. It would be equivalent to the damage other investors may suffer if an insider gets access to "unpublished price-sensitive information (UPSI)" during an "Initial Public Offering (IPO)" and uses it to their advantage!
In fact, compliance under SEBI's insider trading guidelines is very stringent for companies. If SEBI detects any violation, it can impose a fine of ?25 crore or "three times the profit made," whichever is higher. Additionally, individuals guilty of insider trading can face imprisonment for "up to 10 years." In other words, the offence is not just financial but also criminal. When companies are subject to such stringent compliance, how can exchanges like the NSE be allowed to be complacent? Incidentally, the NSE is the world's largest derivatives exchange by trading volume.
During the investigation, SEBI found that the NSE failed to exercise due diligence and that access was not just unequal but selectively advantageous to certain brokers, notably OPG Securities. These were violations not just of internal protocols but of the very trust on which capital markets operate.
The case certainly sent shockwaves across the market. SEBI imposed penalties and even ordered the arrest of a few people, excluding a former NSE CEO and MD. A "disgorgement order" of ?625 crore was issued. Despite this, the storm gradually subsided into procedural ambiguity. The case was referred to the Securities Appellate Tribunal (SAT), where it was quashed, resulting in the dilution of several penalties. The fines initially imposed were reduced, and orders were modified; the hype eventually fizzled out over time. The case faded from public memory as if nothing had ever happened. The exchange resumed normal operations and regained public trust. In fact, it now enjoys an edge over the Bombay Stock Exchange (BSE) in several aspects.
Meanwhile, the exchange applied for an IPO in 2016. The matter has remained unresolved since then. SEBI found many irregularities in the application. Additionally, the exchange faced multiple regulatory and governance challenges. The tenure of former CEO Chitra Ramkrishna brought more complications, as investigations revealed that she had been sharing confidential information with an unidentified "Himalayan Yogi," who allegedly influenced key decisions at the stock exchange. In other words, the exchange's affairs did little to inspire confidence.
Nevertheless, the issues remain unresolved. SEBI has been demanding regulatory compliance and governance reforms. Apparently, the exchange has been pushing hard for SEBI's approval for its IPO. The latest ?1,400 crore settlement proposal may sound attractive, but it leaves many questions unanswered: Is this a genuine reckoning or merely regulatory theatre? Can a payment, however large, replace the need for "public disclosure, reform, governance, and accountability? What message does this send to retail investors? Does it reduce "fairness, integrity, and transparency" to clichéd values? Has the NSE revamped its internal and governance processes to prevent such incidents from recurring?
Most of these questions remain unanswered. All we hear is that a settlement is highly likely. Clearly, SEBI's 2018 Settlement Proceedings Regulations, which allow entities to settle cases without admitting or denying guilt, are being exploited. These consent mechanisms were originally designed to enhance regulatory efficiency, particularly in complex cases, while maintaining deterrence. However, their foundation lies in public confidence in regulatory intent and transparency.
What makes this case deeply problematic is the opacity surrounding the settlement terms. The public still does not know: What reforms has the NSE agreed to implement? What changes have been made to internal accountability frameworks? How will the interests of investors, especially retail participants, be safeguarded? In stark contrast, we are told that a cheque is being sent, and the story will soon be over.
At the heart of this controversy is a more fundamental issue: the nature of regulatory will in India's financial markets. The NSE is no ordinary market participant. When an entity of this magnitude is involved in alleged misconduct, the regulator's duty is not just to penalise but to "cleanse the system".
Here, we observe what political economists refer to as regulatory capture — when regulated entities influence the regulator, either subtly or overtly, due to their size, influence, or systemic importance. In such cases, rules become negotiable, timelines flexible, and penalties tailored to reputation management, disregarding the harm to public interest.
SEBI has a tightrope to walk. Dragging out enforcement indefinitely may weaken market stability, but letting it go too easily undermines deterrence. Institutional investors, especially foreign ones, may see this settlement as a step toward regulatory certainty. Sovereign wealth funds, pension funds, and domestic institutions, such as LIC, may resume engagement. But all this comes with huge reputational risks. Without disclosures and audit trail commitments, the NSE remains vulnerable.
Ideally, this could have been a case study in regulatory resilience. SEBI could have risen to the occasion by demanding Public disclosures on reforms and governance changes implemented, independent audit reports on the NSE's trading architecture, and more. Because what is at stake is not just the NSE's IPO – it is India's regulatory credibility.
SEBI should send a strong message: No cheque should buy silence on crucial compliance and reform.
The NSE may soon go public. But unless its full past is disclosed, it will carry an unspoken liability — one that may not appear on its balance sheet but in the minds of investors who once believed the market was fair, transparent, and safe. We only ask that SEBI stay true to its mandate before granting a no-questions-asked approval for the IPO, upholding the "spirit and the vision it was established with."
.jpg)
 Cedric Prakash
 ICPA
 ICPA
 ICPA
 ICPA
 ICPA
 ICPA
.jpg)
 A. J. Philip
.jpg)
 Jacob Peenikaparambil
.jpg)
 John Dayal